
管理人オススメコンテンツはこちら
「誰もが痛感している残酷な現実|〇〇はあなたのHPがゼロになる直前に傘を奪いにくる」
\NISAやるなら/
今日は【総論】
会社員は知らない!
独立・起業を目指すなら付き合うべき〇〇とは?
というお話をします。
●「こんな会社辞めてやる!」と叫ぶ前に、付き合う〇〇を決めておけ
知り合いが相談を受けたそうです。
「副業にチャレンジする事にしました。
会社員生活を続けるだけだと
明るい未来がイメージ出来なかったからです。
まずはローリスクで副業から始めて
いずれ独立し法人化したいと思っています。
税金の申告などの事も考えると
副業の売上や経費に関しては
事業専用の銀行口座を
使った方がいいですよね?
そこで質問なのですが
オススメの金融機関はありますか?」
とのこと。
ご相談の通り
スモールビジネスとはいえ
事業は事業です。
事業専用の銀行口座は
絶対にあった方がいいです。
専用口座がないと
まともにお金の管理が
できないんですよ。
プライベートと事業が
ごっちゃになってしまうと
本当に管理ができなくなってしまいます。
この記事は、こんな人に向けて書いています
最近は
- 副業を始める人
- 不動産投資にチャレンジする人
がかなり増えてきたように
感じています。
今回は自分で事業を起こして
自由な働き方を手に入れたい人に向けて
付き合うべき金融機関について
お話しします。
たとえば
- 会社を辞めて、フリーランスとして独立したい人
- 会社を辞めて、飲食店などの実店舗を立ち上げたい人
- 会社を辞めて、自分の会社を作って大きく育てていきたい人
- 会社を辞めて、不動産経営で食べていきたい人
このテーマもある意味
『義務教育で教えてくれ!』シリーズの
一つなんですね。
「ずっと会社員だから関係ない」と思った人へ
「ずっと会社員をやるつもりだから
私には関係ないや」
と思った人も
ぜひ最後まで読んでください。
何があるかわからないのが
今の世の中ですから。
もし今の勤務先から
理不尽な目にあわされて
「もうこんな会社辞めてやる!」
なんてことになった時
今回のお話で得た知識が
きっと役に立つはずです。
また特に会社員との
兼業大家(不動産投資家)になりたい人には
めちゃくちゃ使える情報です。
では、本題に入りましょう。
独立・起業を目指すなら付き合うべき金融機関
結論から言います。
普通の会社員は知らないけれど
- 資金コンサル
- 税理士
などのプロは知っている。
あなたが付き合うべき金融機関は
『信用金庫』です。
「何それ?」
という人もいるかもしれません。
今日必ず覚えて帰ってください。
あなたがビジネスをやる時に
力強いパートナーになってくれる
可能性が高い金融機関です。
それも
あなたが住んでいるエリアにある
信用金庫です。
「〇〇は晴れの日に傘を貸し、雨の日に傘を奪う」
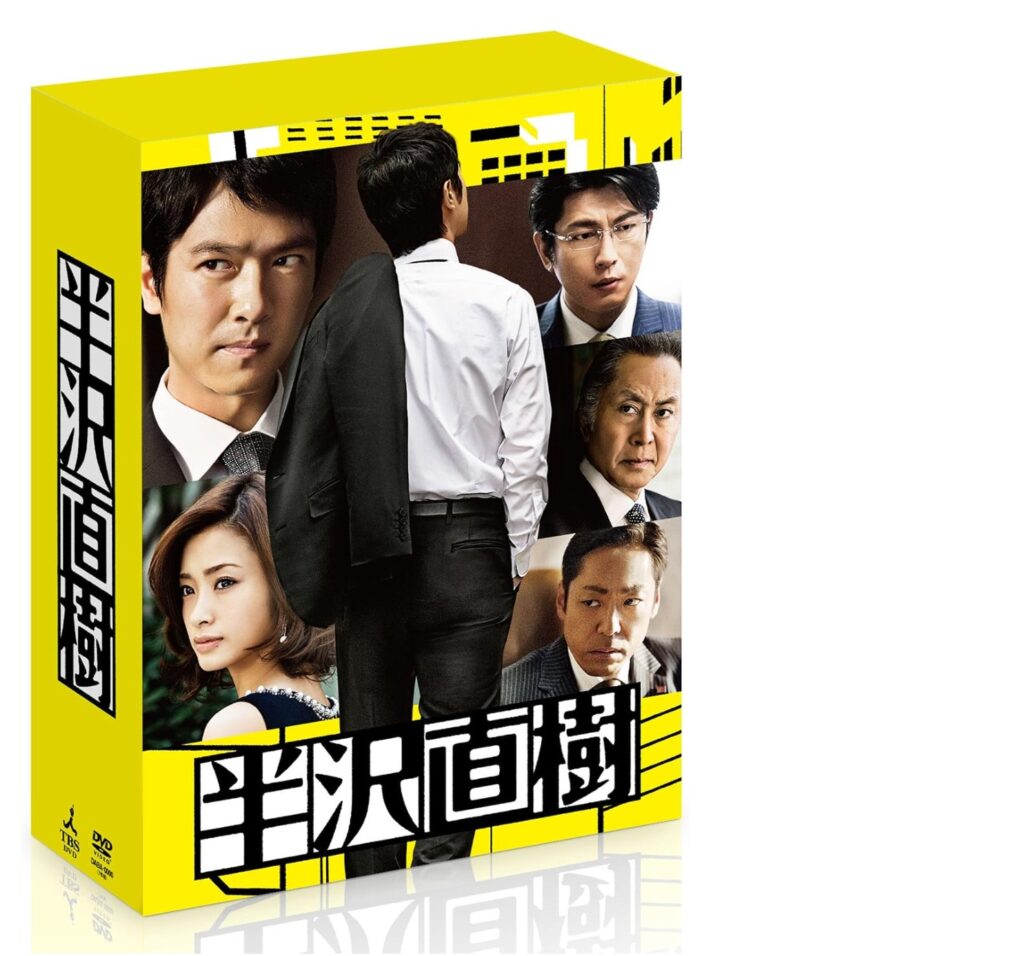
(出展:Amazon)
かつてテレビで
『半沢直樹』というドラマが
放送されていました。
メガバンクに勤める銀行員を描いた
ビジネスドラマです。
こんなセリフを
聞いたことはありませんか?
「銀行は晴れの日に傘を貸して
雨の日に傘を奪う」
要するに
銀行は業績がいい時には
お金を貸してくれるけれど
業績が悪くなると
お金を貸してくれなくなり
回収しにくるということですね。
自分でビジネスをやっている人なら
誰もが痛感している残酷な現実です。
事業主にとって、資金は「HP(ヒットポイント)」
事業主にとって資金というのは
HP(ヒットポイント)
=体力なんですね。
事業主にとって一番の恐怖は
お金が尽きることです。
HPがゼロになったら
ゲームオーバーですからね。
たとえ
「あともう少しで不景気を乗りって
事業が軌道に乗る!」
という状況だとしても
銀行は雨の日に傘(=お金)を
貸してくれません。
それどころか
- その銀行に預けてある会社や個人の預金を凍結する
- 現在融資しているお金を引き上げにかかる
といったことをしてきます。
いわゆる
『貸しはがし』ですね。
親身に相談に乗ってくれる可能性が高いのが〇〇
その一方で
他の銀行より親身に相談に乗ってくれる
可能性が高いのが
『信用金庫』なんです。
その理由は
次回くわしくお話しします。
〜〜〜つづく〜〜〜
Special Thanks college president Ryo.
 管理人_じっちょ
老後のために、まず投資口座を開いておきましょう。
無料・5分で完了です→【公式】楽天証券
●おまけ
≪≪perplexityちゃんによる文章まとめ≫≫
独立・起業を目指すなら、まず事業専用の銀行口座を開設すべきだと筆者は述べています。副業や不動産投資など小さく始める場合でも、プライベートのお金と事業のお金が混ざると、売上や経費の管理、確定申告が難しくなるためです。
そして、付き合うべき金融機関としては「地元の信用金庫」を推奨しています。事業資金は事業主にとって体力のようなもので、資金が尽きれば事業を続けられません。大手銀行は業績が良いときは融資しやすくても、苦しくなると融資を絞ったり回収を強めたりする可能性がある一方、地域に根ざした信用金庫のほうが親身に相談に乗ってくれる可能性が高い、というのが筆者の主張です。
会社員の今でも、将来の独立や転職に備えて知っておくべき話としています。
Citations:
[1]https://www.shinkin.org/whatisshinkin/contentsa/contentsa1.html
[2]https://www.shinkin.org/torikumi/area/chiiki/
[3]https://media.crefty.jp/smallbiz/business-bank-account-separation/
[4]https://www.tamashin.jp/business/finance/index.html
[5]https://www.shinkin.co.jp/alshin/houjin/solution/index.shtml
≪≪Chat-GPTくんによる英訳≫≫
Today’s Topic: The Big Picture
What Salaried Employees Don’t Know: Which Financial Institutions Should You Build Relationships With If You Want to Start Your Own Business?
That’s what we’re going to talk about today.
【Before You Shout, “I’m Quitting This Job!”, Decide Who You Need on Your Side】
An acquaintance of mine was recently asked for advice.
Here’s what the person had to say:
“I’ve decided to give a side business a try.
Simply continuing to work as a salaried employee didn’t give me a clear picture of a bright future.
My plan is to start small with minimal risk and eventually become independent and incorporate my business.
Considering things like tax returns, I assume it’s better to use a separate bank account exclusively for my business income and expenses, right?
So here’s my question:
Are there any financial institutions you would recommend?”
That was the question.
As the person rightly pointed out, even if you’re running a small business, it’s still a business.
Having a dedicated business bank account is absolutely essential.
Without one, you simply can’t manage your money properly.
Once your personal finances and business finances get mixed together, keeping track of everything becomes genuinely difficult.
~Who Is This Article For?~
Recently, I’ve noticed what seems to be a significant increase in the number of people who are:
- Starting side businesses
- Trying their hand at real estate investing
This article is for people who want to start their own businesses and gain the freedom to work on their own terms.
Today, I’m going to talk about the financial institutions you should build relationships with.
For example, this includes people who want to:
- Quit their jobs and become self-employed freelancers.
- Leave their jobs and open a brick-and-mortar business, such as a restaurant.
- Quit their jobs, start their own companies, and grow them into successful businesses.
- Leave their jobs and make a living through real estate investing.
In a way, this topic also belongs to my series:
“Why Don’t They Teach Us This in Compulsory Education?!”
~For Those Who Think, “This Doesn’t Apply to Me Because I’ll Always Be an Employee”~
Some of you might be thinking:
“I plan to remain a salaried employee for the rest of my career, so this has nothing to do with me.”
Even so, I encourage you to read this article to the end.
In today’s world, you never know what might happen.
What if your current employer treats you unfairly, and you finally reach the point where you shout:
“That’s it! I’m quitting this job!”
The knowledge you gain from this article could prove invaluable when that day comes.
This information is also extremely useful for people who want to invest in real estate while keeping their day jobs.
In Japan, such investors are often referred to as fukugyo ooya—landlords who operate rental properties alongside their regular employment.
Now, let’s get to the main topic.
~If You Want to Start Your Own Business, Build a Relationship With a Credit Union~
Let me give you the conclusion first.
Most salaried employees don’t know this, but professionals such as:
- Business finance consultants
- Tax accountants
are well aware of it.
The financial institution you should build a relationship with is a credit union.
In Japan, these institutions are called shinkin banks (信用金庫).
Some of you might be thinking:
“What’s that?”
Make sure you remember this one thing before you leave today.
A shinkin bank is a financial institution that could become a powerful partner when you start running your own business.
And I’m talking specifically about a shinkin bank in the area where you live.
~“Banks Lend You an Umbrella When the Sun Is Shining, Then Take It Away When It Rains”~
(Image: Naoki Hanzawa)
Source: Amazon
A while ago, a Japanese TV drama called Naoki Hanzawa aired.
It was a business drama about a banker working for a major Japanese commercial bank.
Have you ever heard this line?
“Banks lend you an umbrella when the sun is shining, but take it away when it rains.”
In other words, banks are willing to lend you money when your business is doing well.
But when your business starts struggling, they may stop lending you money—and start trying to recover what you already owe them.
If you run your own business, you probably understand this harsh reality all too well.
~For Business Owners, Cash Is Like HP (Hit Points) in a Video Game~
For a business owner, money is essentially HP (hit points)—your business’s lifeblood.
The biggest fear for any business owner is running out of money.
Once your HP reaches zero, it’s game over.
Imagine a situation where you’re thinking:
“Just a little longer, and we’ll get through this recession and get the business back on track!”
Even then, a bank may refuse to lend you money when you need it most.
Worse still, it may take measures such as:
- Freezing the company’s or business owner’s personal deposits held at that bank.
- Trying to call in existing loans and recover the money it has already lent.
This is commonly referred to in Japan as kashihagashi—the practice of abruptly withdrawing or refusing to renew existing business financing, potentially putting a struggling company under even greater financial pressure.
~Which Financial Institutions Are More Likely to Give You a Helping Hand?~
On the other hand, there is one type of financial institution that is more likely than other banks to listen to your concerns and work with you to find a solution.
That institution is a shinkin bank (信用金庫).
I’ll explain why in detail in the next article.
Special Thanks OpenAI and Perplexity AI, Inc